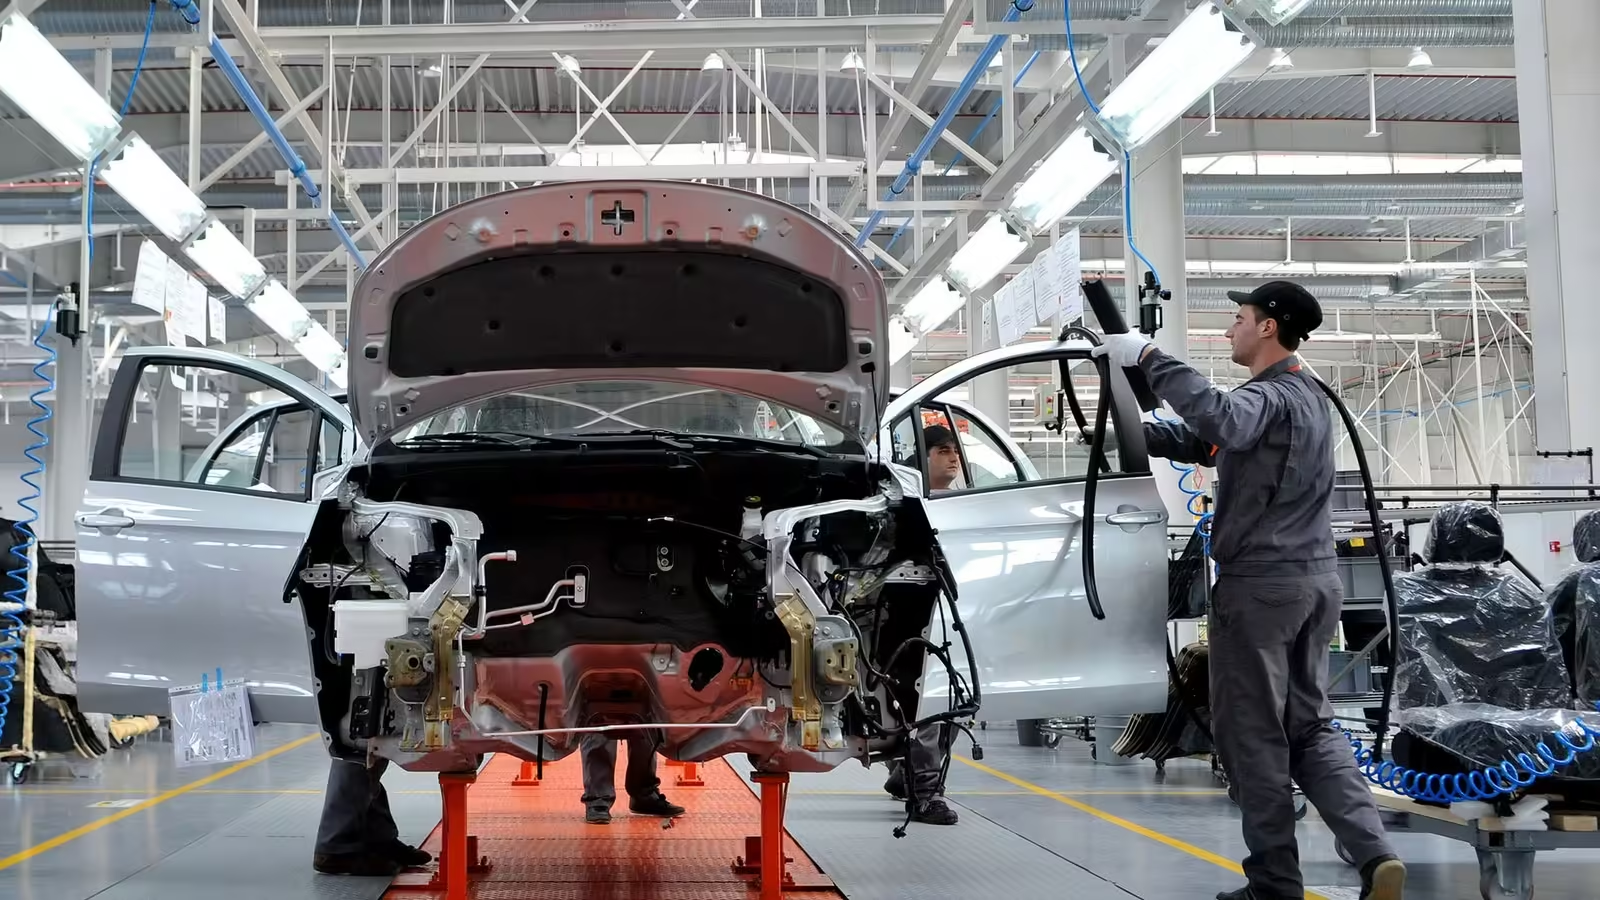

- Rivian Automotive reported third quarter 2026 results with 19,751 vehicles produced and 19,248 delivered from its Normal, Illinois plant, and confirmed full year 2026 delivery guidance of 65,000 to 70,000 units.
- The tight gap between production and deliveries, combined with reaffirmed annual volume targets, highlights how effectively Rivian Automotive is converting factory output into customer handovers. This is a key test of execution for any high capital EV manufacturer.
- We will now look at how Rivian Automotive’s reaffirmed 2026 delivery guidance shapes the broader investment narrative around its scaling plan.
Compare Rivian Automotive’s scaling story with other high output manufacturers by scanning our curated list of 39 power grid technology and infrastructure stocks.
Rivian Automotive Investment Narrative Recap
To own Rivian Automotive, you need to believe the firm can turn growing production into a sustainable, higher volume business before cash requirements bite too hard. The latest quarter shows nearly one to one conversion of units built to units delivered and a reaffirmed 2026 delivery range, which points to operational consistency rather than a step change.
Right now, the key short term catalyst is evidence that rising volumes start to ease unit costs and cash burn. The biggest risk remains the opposite outcome, where heavy spending on new platforms and facilities meets any demand wobble or policy change and forces more aggressive funding and potential dilution.
The reaffirmed 2026 delivery guidance of 65,000 to 70,000 vehicles is the announcement that really matters here. It anchors expectations for how quickly Rivian Automotive intends to scale its current plant and sets a reference point for whether supplier contracts, staffing and logistics are keeping pace with the plan.
For you as a shareholder, that delivery range ties directly into the catalysts around cost structure and future platforms like R2. Hitting or missing these volume milestones will feed into views on when losses might narrow, how much extra capital could be needed and how resilient the business looks in a crowded EV market.
Rivian Automotive’s narrative projects US$20.8b revenue and US$736.7m earnings by 2029. This scenario assumes revenue grows at 52.3% per year and earnings improve by roughly US$3.9b from a loss of US$3.2b today.
Uncover how Rivian Automotive’s fair value indicates a 32% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some analysts see the recent production and delivery update very differently. The most pessimistic group already assumed Rivian Automotive would reach only about US$12.3b of revenue and US$437.2m of earnings by 2029, with a P/E near 72x. That cohort worries supplier fragility could cap R2 volumes, so these fresh numbers may force a rethink.
Explore 3 other Rivian Automotive fair value estimates, including one that suggests it could be worth just $19.23!
The Verdict Is Yours
Don’t just follow the ticker. Dig into the data and build a conviction that’s truly your own.
Looking For More Investment Ideas Beyond Rivian Automotive?
If this Rivian Automotive update has sharpened your thinking about execution risk and upside potential, it can help to compare it with companies that score well on different fundamentals using the Simply Wall St Screener.
- For investors who want quality at a reasonable entry point, review a curated 27 high quality undervalued stocks that combine strong fundamentals with prices that may be out of step with their underlying metrics.
- If capital preservation and steadier profiles matter more to you than aggressive growth, filter for 31 resilient stocks with low risk scores that show lower overall risk scores and more resilient financial profiles.
- When you want robust finances to be the first hurdle any idea must clear, start with a list of solid balance sheet and fundamentals (25 results) and focus only on businesses with cleaner debt levels and stronger balance sheets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email [email protected]
Source: simplywall.st