
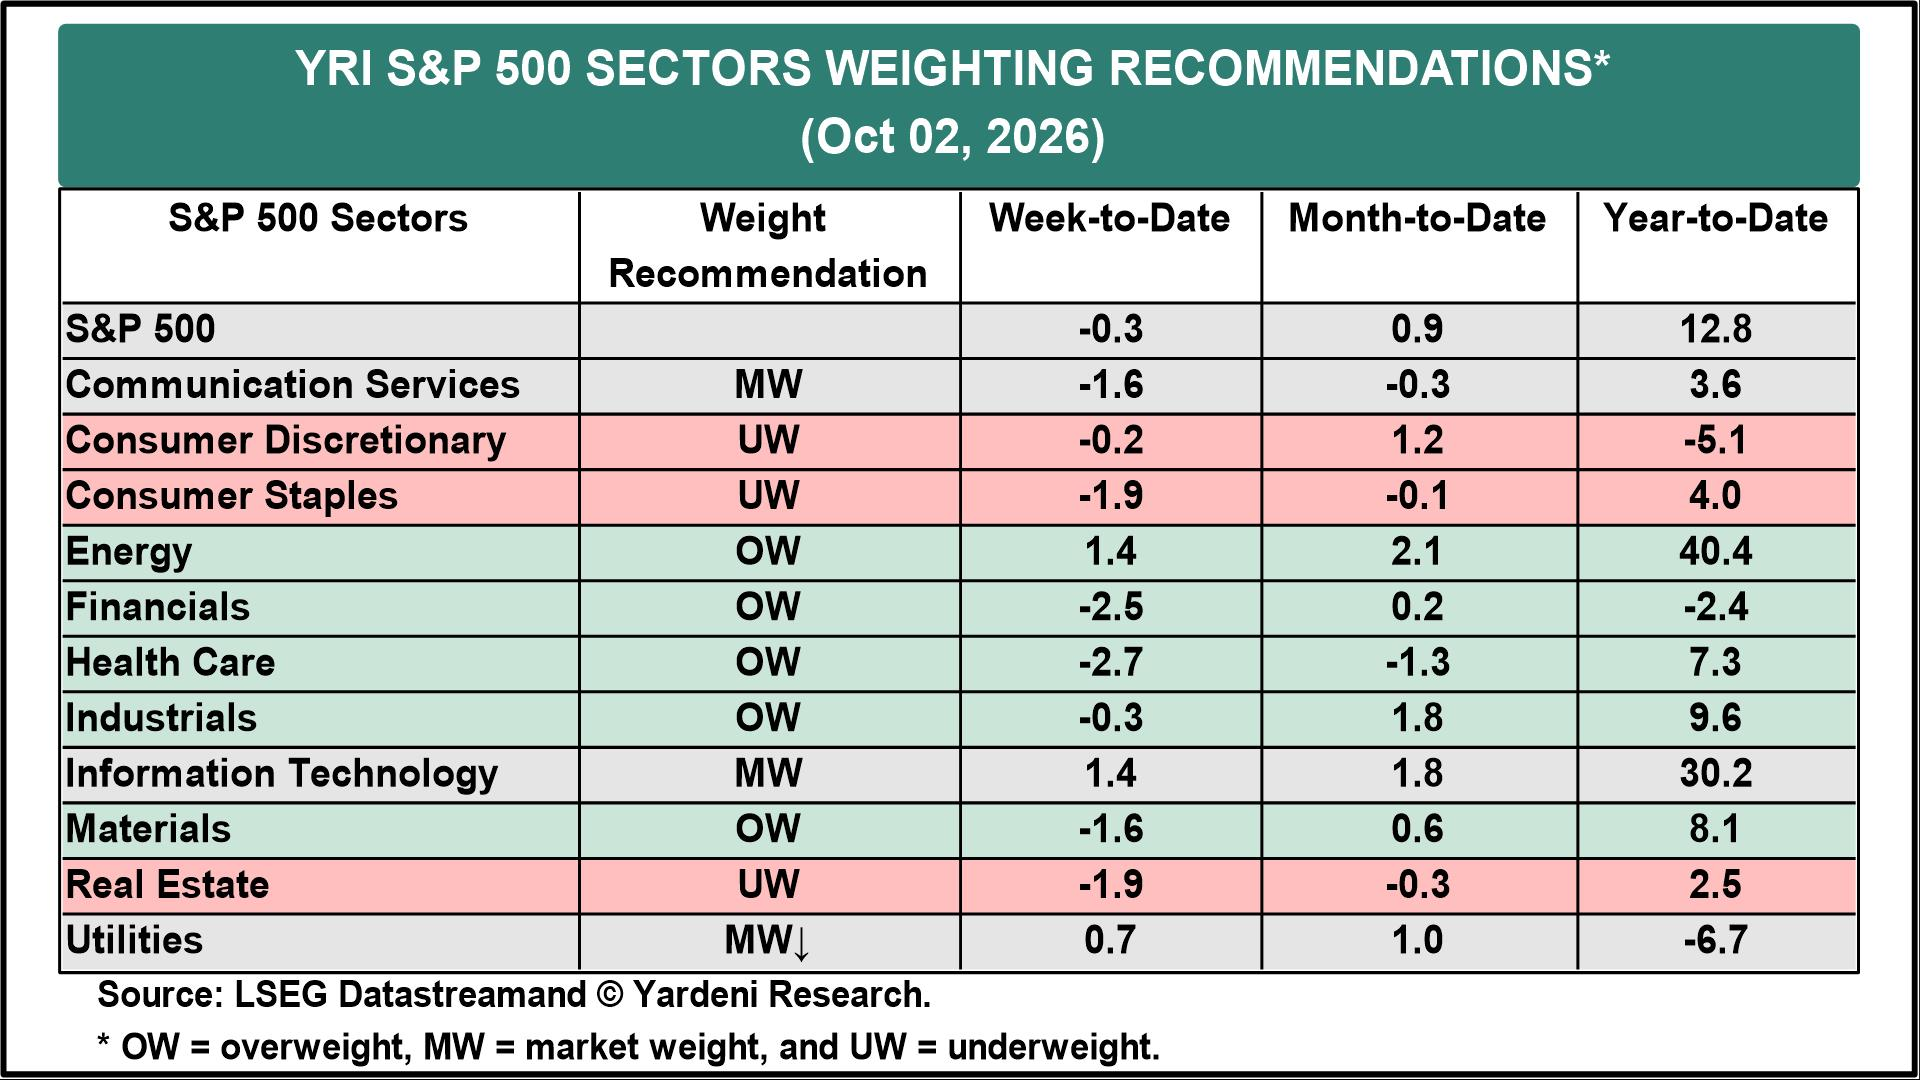
The S&P 500 fell 0.3% last week. Energy (OW) and Information Technology (MW) led the week’s sector performance derby, both up 1.4%. Utilities (MW) was the only other gainer, up 0.7%. Health Care (OW) was the weakest at -2.7%, followed by Financials (OW) at -2.5%.
On a ytd basis, Energy is up 40.4%, the best of the 11 sectors, and IT is second at 30.2% (chart).
We lowered our rating on Utilities last week from overweight to market weight. We argued that the sector’s valuation discount rewarded investors for waiting out the bond market. The 10-year Treasury yield has since risen to 5.28%, after peaking at 5.34% earlier this week. We don’t expect the sector’s multiple to recover until yields stop climbing.
Here’s more on Information Technology, Consumer Discretionary, and Consumer Staples:
(1) Information Technology. Micron is now the third-largest company in the S&P 500 Semiconductors industry. Its market value of $1.21 trillion trails only those of Nvidia and Broadcom and leads AMD at $1.03 trillion. Micron’s stock price is up 276.6% ytd, ahead of AMD at 196.0%, Nvidia at 25.4%, and Broadcom at 2.6% (chart). Its forward revenues are $271.3 billion, and its forward profit margin is 73.1%. It trades at just 6.3 times forward earnings.
Source: www.yardeniquicktakes.com