Getty Images Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below. If you have a child under 18, they probably have a Trump Account now — whether you signed them up or not. On Oct. 1, the Treasury Department said (1) it had finished automatically enrolling every eligible
Getty Images
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
If you have a child under 18, they probably have a Trump Account now — whether you signed them up or not.
On Oct. 1, the Treasury Department said (1) it had finished automatically enrolling every eligible child under 18 with a valid Social Security number.
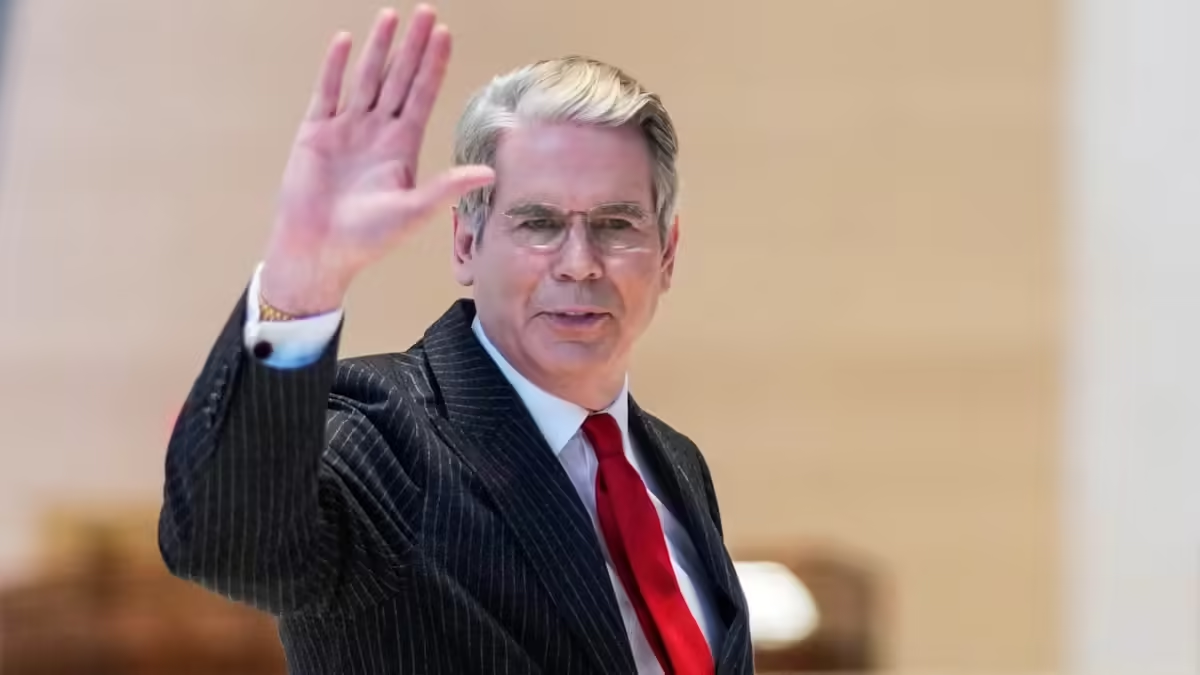
“Millions of children have already enrolled in Trump Accounts. With automatic enrollment, over 60 million more eligible children now have an account ready to be claimed,” Treasury Secretary Scott Bessent said in a statement.
Top Picks
The key word there is “claimed.”
An account Treasury opened on your child’s behalf can’t accept money from you, the grandparents or an employer until a parent or guardian claims it. And for kids born from 2025 through 2028, it won’t get the government’s $1,000 seed deposit unless an adult specifically asks for it, under Treasury’s new rules (2).
Here’s why Treasury stepped in — and what parents need to do now.
Why the Treasury stepped in
Until Oct. 1, parents had to opt in by filing IRS Form 4547 (3) with their tax return, through their IRS online account or in the Trump Accounts app. Most families didn’t.
Before July 30, the IRS had processed about 5.6 million electronic sign-up forms for an estimated 73.37 million eligible children, according to Treasury figures in the Federal Register. That’s fewer than 1 in 13 kids. Among children in households with no reported income or no tax return on file, it was about 0.1%.
Bessent told the House Financial Services Committee (4) on Sept. 15 that 7 million to 8 million children had signed up. That’s still only about 1 in 10.
Treasury had said in March that it couldn’t auto-enroll kids without exposing protected tax information. Its new rules get around that by pooling the accounts’ investments in a single master trust. Treasury estimated that an opt-in system would have topped out near 50% of eligible families. It based that on Maine’s Alfond Grant, a $500 newborn grant that saw about 40% enrollment when parents had to sign up on their state tax return. Now it expects nearly every eligible child to have an account.
The $1,000 won’t show up automatically
The catch: Treasury can open the account for your child, but it can’t request the $1,000 for you. The election has to come from the adult who expects the child to be their qualifying child for tax purposes, typically a parent or guardian.
The seed deposit is part of a separate federal pilot program, and it’s only available to U.S. citizens born between Jan. 1, 2025, and Dec. 31, 2028, who have a Social Security number. Older kids can still have a Trump Account. They just aren’t eligible for the government’s $1,000.
Families have until Dec. 31 of the year the child turns 17 to make that election, under rules the IRS proposed in March (5). Waiting that long, though, means giving up years of growth.
Boston-based nonprofit Commonwealth, which works on financial security for low- and moderate-income households, found in a July survey (6) that just 5% of eligible lower-income parents had opened an account. It projects that about 14.4 million children born from 2025 through 2028 will qualify for the $1,000, including about 5.8 million from low- and moderate-income households. Using the earned income tax credit as a guide, it estimates roughly 20% (7) of eligible babies could miss out, leaving about $2.88 billion unclaimed.
In the same rules, Treasury ran the numbers using historical returns for a broad index of U.S. stocks across birth cohorts from 1926 to 2006. At the median, $1,000 invested at birth grew to about $6,180 by age 18. In a strong stretch for the market (the 90th percentile), it reached about $13,800. In a weak one (the 10th percentile), it still grew to about $2,980.
Timing matters, too. Under the same analysis, $1,000 invested at age 5 grew to a median of about $3,990 by 18, and $1,000 invested at age 10 grew to about $2,460.
Past returns don’t guarantee future results, of course, and economists have pushed back on some of the rosier projections for these accounts. But on Treasury’s numbers, a deposit at birth ended up worth more than twice as much as one made at age 10.
Step 1: Claim it
Claiming is how you take control of the account Treasury opened. You can do it in the official Trump Accounts app for iOS and Android or on the Trump Accounts web portal (8). There, you’ll verify your identity and your relationship to your child, review their information and accept the account terms.
Don’t expect it to be as quick as filing Form 4547. Because the account itself counts as protected tax information, Treasury and the IRS say claiming requires more information than the form does.
If your child was born from 2025 through 2028, make sure the $1,000 election is on file, too. That’s still done with Form 4547, which you can file in the Trump Accounts app or through your IRS online account (9). The IRS says the online route takes about five to 10 minutes with an ID.me (10) login, your child’s Social Security number, date of birth and address.
Until you claim it, the account can still collect money from governments and charities. For kids born before 2025, that’s where the Dell money comes in. Michael and Susan Dell pledged $6.25 billion to put $250 into the accounts of 25 million children born from 2016 through 2024 who live in ZIP codes where the median household income is below $150,000. Invest America, which hosts the gift’s official eligibility page (11), says it now deposits $250 directly into eligible kids’ auto-enrolled accounts, with no application required. You’ll need to claim the account to see it.
Park the cash while you wait
Your savings don’t have to sit idle in the meantime, though. If you plan to contribute once you claim the account, or you just want a cushion for a growing family, you can keep that cash somewhere it earns interest.
A high-yield account like a Wealthfront Cash Account can be a great place to grow your uninvested cash, offering both competitive interest rates and easy access to your money when you need it.
A Wealthfront Cash Account currently offers a base rate APY of 3.55% through program banks. With a new client boost and direct deposit incentive, referred clients can earn up to a 4.55% APY.
That’s 10 times the national deposit savings rate, according to the FDIC’s September report.
Once the account is claimed, family, friends and employers can start adding to it. But Trump Accounts come with tight rules.
Until the year your child turns 18, the money can only be invested in low-cost funds that track a broad index of mostly U.S. stocks, with no leverage and annual fees capped at 0.1%.
Contributions from family, friends and employers are capped at $5,000 a year combined, a limit that will be adjusted for inflation after 2027. The $1,000 pilot deposit and group contributions from governments or charities, including the Dell money, don’t count toward that cap. Employers can kick in up to $2,500 a year tax-free, but that does count.
Plenty of employers plan to. More than 50 companies, including JPMorgan Chase, BlackRock, Nvidia and Uber, have committed to contribute (12) to accounts for employees’ children. If you work for a large company, ask HR whether yours is on the list. That money can’t land until you’ve claimed the account.
And the money is largely locked up. Withdrawals generally aren’t allowed until Jan. 1 of the year your child turns 18. After that, the account follows traditional IRA rules: If you pull money out before age 59½, the taxable portion is generally subject to income tax plus a 10% penalty (13). Exceptions include qualified education expenses and up to $10,000 toward a first home.
If you’d like to build up the cash for those contributions without feeling the pinch, Acorns can help automate the process.
With Acorns’ Round-Ups® feature, you can automatically invest spare change from everyday purchases into a diversified portfolio of ETFs. Buy something for $3.25, for example, and Acorns can round the purchase up to $4. That extra 75 cents becomes an investment in your future.
And while you’re investing in your kids, don’t forget yourself. With Acorns Later, you can invest for retirement in an IRA portfolio that automatically adjusts as you age and set recurring contributions starting at just $5 a day, week or month.
Sign up today, make your first successful recurring investment of at least $5 and get a $20 bonus investment.
We rely only on vetted sources and credible third-party reporting. For details, see ourethics and guidelines.
U.S. Department of the Treasury (1); Federal Register (2), (5); Trump Account (3), (8); CNBC (4), (7); Build Commonwealth (6); Internal Revenue Service (9), (13); ID.me (10); Invest America (11); Axios (12)
This article provides information only and should not be construed as advice. It is provided without warranty of any kind.
Reportage Media Is a Global News Platform Covering the Latest Developments and Breaking Stories from Around The World, Including World News, Business, Finance, Technology, Health, Politics, Science, Entertainment, Sports, and More.