


South Africa’s 2026-27 winter crop production is estimated at 2.67 million tonnes, up 2% year on year. While this figure is optimistic, it overshadows sector challenges that have persisted since the start of the season.
For example, the higher input costs weighed on finances as the season began a few months after the U.S.-Iran war, with fertiliser and fuel prices surging.
Drier weather in the Western Cape over the past few months added another challenge. As a result, farmers feared they would reduce the area planted for crops.
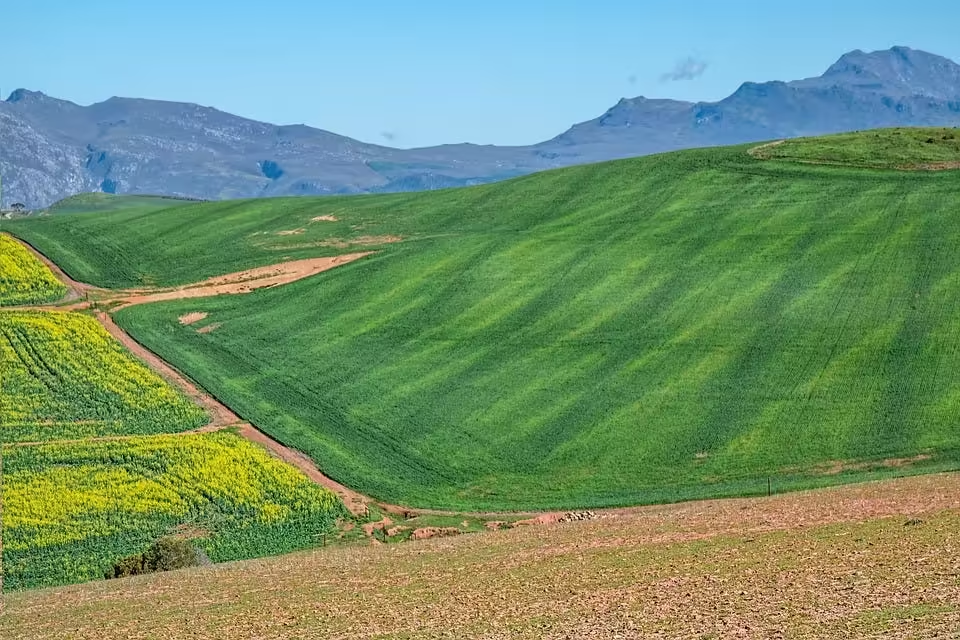
Fortunately, they still planted a decent area of 851 510 hectares, up 1% from the 2025-26 season. About 57% of the area is wheat, 23% is canola, and the rest is barley, oats and sweet lupins. Most crops show a mild annual increase, except wheat, which declined somewhat in 2025-26.
Looking at the detailed data, the 2026-27 barley harvest is estimated at 414 640 tonnes, up 20% year on year. The canola harvest is estimated at 377 770 tonnes, up 20% from the 2025-26 harvest.
The oats harvest is estimated at 55 850 tonnes, up by 28% from the 2025-26 season. The 2026-27 sweet lupines harvest is at 18 000 tonnes, up 1%. The main driver of the higher harvest prospects for these winter crops is the expansion in area planted.
On the negative, South Africa’s 2026-27 winter wheat harvest is estimated at 1.81 million tonnes, down 5% year on year. This is the lowest harvest in eight years.
The decline in area planted, combined with the prospect of poor yields due to dryness in parts of the Western Cape over the past few months, is a major factor behind the expected lower harvest.
Consequently, South Africa will likely increase wheat imports to around 2.0 million tonnes, up from 1.9 million tonnes last season. Fortunately, the imports may not be a major challenge as the global wheat market is well supplied.
For example, in September 2026, the International Grains Council placed the 2026-27 global wheat production forecast at 820 million tonnes. Looking at this figure year on year may be worrying, signalling a 3% drop from the 2025-26 season.
But over the long term, a harvest of 820 million tonnes is well above the long-term level of about 790 million tonnes.
The only near-term challenge, and the major driver of price increases, is disruption to shipping infrastructure in Ukraine because of the Russia-Ukraine war. If tensions in the region ease and shipment disruptions decrease, global wheat prices should normalise.
Source: wandile.substack.com

