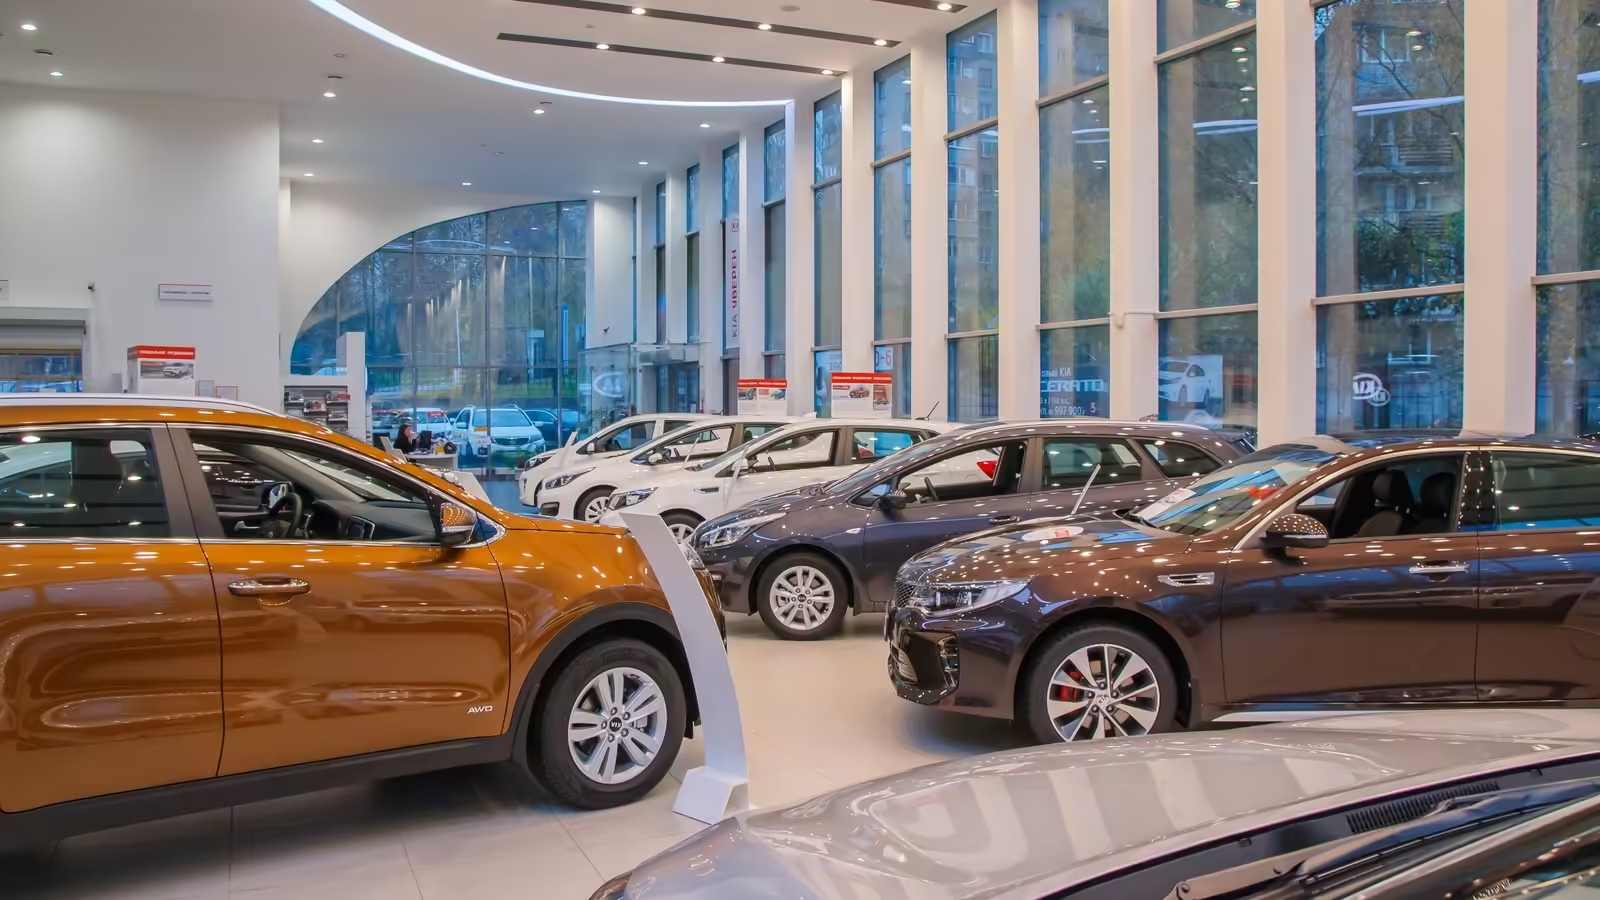

- Asbury Automotive Group has opened its redeveloped Herb Chambers Toyota dealership in Medford, expanding showroom, parking, and service capacity while adding around 100 local jobs.
- The larger, higher throughput Herb Chambers Toyota facility gives Asbury Automotive Group more room to grow fixed operations and manage execution risk from the Tekion rollout during the Herb Chambers integration.
- We will look at how Asbury Automotive Group’s investment narrative is affected by the Medford service capacity expansion and job additions.
Scan how Asbury Automotive Group compares with other operators growing service-heavy footprints by reviewing our curated list of list of solid balance sheet and fundamentals (25 results)
Asbury Automotive Group Investment Narrative Recap
For an investor to stay with Asbury Automotive Group, the core belief is that fixed operations, digital retail tools and the Herb Chambers footprint can together support earnings over time, even while headline vehicle volume and pricing move around. The Medford expansion fits that view by adding higher throughput service capacity, although on its own it does not fundamentally change the short term story.
Right now, the key near term swing factor is still Tekion execution, because early conversion periods have brought disruption to customer pay service and gross profit. The Medford facility provides more physical room to absorb that friction and to grow high margin work per day. However, the main risk remains a longer than expected Tekion related drag on margins and leverage while buybacks continue.
The Herb Chambers integration, particularly the enlarged Toyota site, is the clearest recent development tied to this news. The company gains more service bays, more parking and more showroom space in a single high traffic, higher income market. That matters because the bullish thesis leans heavily on recurring parts and service activity and higher throughput rooftops to support long run gross profit.
At the same time, Asbury Automotive Group still carries the execution questions that existed before Medford reopened. Tekion rollout disruption, Total Care Auto deferrals and net leverage at 3.4x all remain in the background. The enlarged Boston area service footprint can support future fixed absorption and technician productivity, but investors still need to watch how quickly converted stores move from disruption to stable margin contribution.
Asbury Automotive Group Consensus Setup After the Medford Expansion
Asbury Automotive Group’s narrative projects US$21.2b in revenue and US$638.9m in earnings by 2029, based on analyst consensus. This rests on 5.6% yearly revenue growth and an earnings increase of about US$129m from US$509.5m today.
Uncover why Asbury Automotive Group’s fair value indicates that there may be a 54% potential upside to its current price before that discount starts to close.
Exploring Other Perspectives
Some of the most optimistic analysts focus heavily on Tekion productivity as the key swing factor for Asbury Automotive Group, rather than the Medford service build out. Before this news, they were penciling in about US$21.4b of revenue and US$644.9m of earnings by 2029. You might see the Medford expansion and decide those pre news assumptions either look too cautious or too aggressive. This is why it can help to compare several viewpoints before settling on your own.
Explore 2 other Asbury Automotive Group fair value estimates, including one that suggests up to 203% upside from the current price!
Form Your Own Verdict
Don’t just follow the ticker. Dig into the data and build a conviction that’s truly your own.
Looking for more investment ideas beyond Asbury Automotive Group?
Once you have formed a view on Asbury Automotive Group, it can help to compare that thesis with other opportunities that fit different risk, income, and balance sheet profiles. The Simply Wall St Screener gives you a quick way to do that side by side.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We’ve created the ultimate portfolio companion for stock investors, and it’s free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email [email protected]
Source: simplywall.st