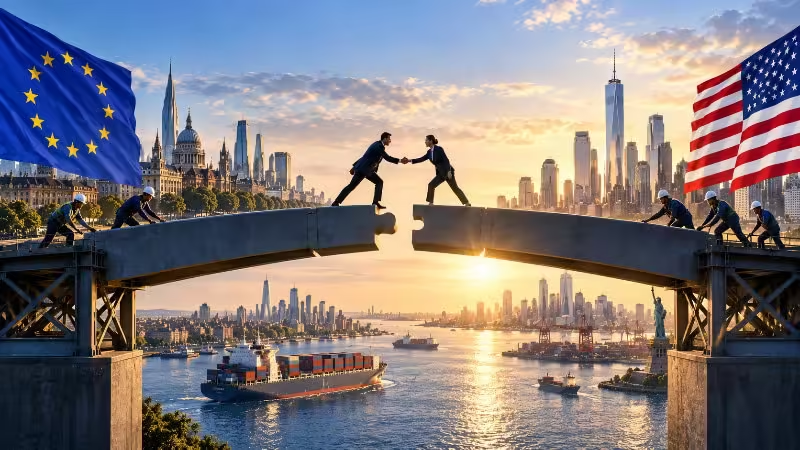

Closing the gap with the United States requires deeper European integration and a more practical transatlantic partnership, not a retreat from openness.
Europe will not close its economic gap with America by putting greater distance between their economies. It will do so by making its own market work better and giving transatlantic trade and investment a more dependable basis. For Europeans, those objectives should belong to the same growth strategy.
The scale of the challenge is clear. Eurostat valued the European Union’s GDP at €18.8 trillion in 2025. Converted at the year’s average exchange rate, that was approximately $21.3 trillion, against US output of $30.8 trillion. America’s economy was therefore roughly 45 per cent larger at prevailing prices and exchange rates. Here, Europe means the EU’s 27 member states, not the euro area or the whole continent.
Currency movements can change a dollar-denominated ranking without changing the volume of goods and services produced. Purchasing-power adjustments, which account for differences in local prices, bring the two economies much closer in aggregate size. Yet Eurostat’s 2025 figures still put US GDP per person 38 per cent above the EU average on that basis. Similar overall scale and a substantial per-person gap can coexist.
Neither measure settles every argument about living standards. GDP does not tell us how income is distributed, how secure households feel or how they value public services and leisure. Nor should Europe treat every feature of the American economy as something to copy. But the qualification cannot become an alibi. Sustaining Europe’s social ambitions requires a stronger capacity to generate income, finance innovation and build the infrastructure on which future prosperity depends.
The more useful comparison concerns the conditions under which businesses grow; recent European Central Bank analysis finds that firm creation in Europe is broadly comparable with the United States, while expansion into larger, more productive enterprises is much harder. Fragmented markets and limited access to growth capital constrain that process. The challenge is less to persuade Europeans to have ideas than to give viable businesses room to develop them.
A GDP total is not the same thing as a market that a company can readily use. For an entrepreneur, economic scale means the ability to raise money, establish operations and win customers across borders. Corporate forms, insolvency procedures and the predictability of enforcement influence the cost of expansion. Europe’s scale must be available in commercial practice, rather than merely visible in its statistics.
This should change the way Europe talks about its American partnership; US economic strength offers European companies customers, financing and opportunities to commercialise their work. European success, in turn, creates demand and investment opportunities for American businesses. Competing for the next factory or breakthrough need not mean treating a partner’s prosperity as a strategic loss. An economy can gain relative strength while helping its trading partners become richer.
The commercial foundation is already substantial. According to the European Commission, two-way goods trade reached about €911 billion in 2025, while mutual investment positions stood at €4.8 trillion in 2024. Services, including intellectual property and professional and technical activities, add another essential dimension. The relationship extends well beyond products crossing a border: it includes businesses operating, investing and serving customers in each other’s markets.
For that reason, a bilateral goods balance is a poor scorecard for the partnership. An imported machine can raise a domestic factory’s productivity; a foreign technology supplier can help a local company reach new customers. Such benefits do not appear neatly in the net trade figure. The better questions concern value created, competitive pressure, investment and purchasing power. Trade policy should improve those outcomes rather than simply reward the larger surplus.
Consumers belong at the centre of this argument. A credible European growth strategy should make households better able to purchase goods and services, including those supplied by American firms. That means raising productivity and addressing structural costs, from energy to housing, rather than relying on overseas demand to compensate indefinitely for weak opportunities at home. Stronger domestic demand and a competitive export sector should reinforce one another.
The same reasoning applies to investment. ECB research published this September highlights the substantial share of euro area household financial assets held in deposits and the lower participation in capital markets than in the United States. These are differences in financial structures and incentives, not evidence that Europeans lack resources. The task is to offer suitable, transparent ways of financing long-term growth while respecting savers’ need for liquidity and security.
More integrated European capital markets would help. So would easier cross-border business operations and a credible route from research funding to commercial deployment. American investors should be welcome participants in that process. Europe’s objective should be to become a better place to build companies, not to make foreign financing suspect. Attracting international capital and retaining the conditions for productive activity at home are compatible ambitions.
The best European contribution to the transatlantic relationship therefore begins inside Europe. A common market should offer a growing business a realistic prospect of reaching customers across the Union without repeatedly absorbing avoidable administrative costs. More predictable permitting, better-connected electricity networks and fewer obstacles to cross-border services would make Europe more attractive to its own entrepreneurs and to investors from abroad. These are practical expressions of European ambition.
Internal reform, however, should be matched by a more focused transatlantic agenda. Brussels and Washington should identify a limited set of commercial problems they can solve together, give officials clear responsibilities and judge progress by what changes for businesses. There is no need to wait for complete political agreement or an all-encompassing treaty before making ordinary transactions easier.
Product testing is one place to start. Where technical evidence demonstrates equivalent protection, wider recognition of each other’s assessments could reduce unnecessary duplication. Digital customs documentation and more consistent administrative procedures could also help smaller exporters, for whom a fixed compliance cost can determine whether entering a market is worthwhile. Cooperation should preserve legitimate standards while questioning the expense of proving the same thing twice.
Investment cooperation should be equally concrete. Joint research needs pathways to commercial projects; promising companies need access to customers as well as capital. Energy infrastructure, industrial technology and applied artificial intelligence offer useful areas in which to organise partnerships. Success should be measured in operating facilities, new products and sustained investment, rather than the headline value of announcements.
Predictability deserves particular attention. Exchange-rate risk can often be hedged. The risk that a certification route or a market-access assumption will change midway through a project is harder to contain. A business contemplating a long-lived investment must consider whether the conditions on which it relies will endure. ECB research has linked uncertainty about US economic policy to weaker lending to firms in the euro area. The wider lesson is straightforward: uncertainty travels through financial relationships as well as supply chains. Clear procedures, consultation and reliable implementation have an economic value of their own.
None of this requires identical regulatory philosophies or the suspension of competition. Europe should remain able to set its own standards and defend legitimate interests. The United States will do the same. A durable partnership must work through differences rather than assume they will disappear. Reciprocity should mean credible opportunities on both sides, supported by institutions capable of resolving disagreements before they overwhelm the wider relationship.
There is also a clear American interest in European reform. A more integrated EU would give US companies a more accessible market and stronger commercial partners. Europe’s investment needs could support demand for American equipment, expertise and services. Washington should regard European economic dynamism as an opportunity, just as Brussels should recognise that partnership can advance, rather than diminish, European agency.
That partnership must remain compatible with multilateralism. Closer transatlantic cooperation should help make international commerce more predictable for others, including countries outside the relationship. That means supporting workable WTO rules and credible dispute settlement, while designing technical cooperation so that other economies can participate where appropriate. Europe and America can pursue mutual advantages without turning the Atlantic into an exclusive economic club. An open system gains credibility when its major participants make cooperation work in practice.
The proper European response to America’s economic lead is therefore to become a partner with more to offer: a genuinely accessible continental market, stronger companies and greater investment capacity. That would make Europe more prosperous and give the United States a more valuable counterpart. The Atlantic is already a vast commercial relationship. In an uncertain world, neither side should be content merely to preserve it.
Written by João Maria Botelho.
Have you read?
Want More Creativity and Less Burnout? Make Time for Play.
Ken Griffin’s Miami Beach Helipad Advances Despite Neighbour Opposition.
How to Know When an Argument Is Worth Having.
A CEO’s Back-to-School Playbook for Working Parents.
How Reading Together Helped Transform My Working-Parent Guilt.
Source: ceoworld.biz